 Main menu


Las Vegas
Future Less Bright for Brightline High-Speed Vegas Rail
Posted on: September 29, 2026, 06:25h.
Last updated on: September 29, 2026, 11:42h.

Key Points
- Brightline Holdings recently filed for bankruptcy, but Brightline West remains a separate legal entity
- Initial construction on the Las Vegas high-speed rail station appears to have stalled
- The delayed train project still needs a $6 billion federal loan to close a major funding gap


Brightline Holdings and affiliated Florida parent companies—sister companies to Brightline West, the company that still says it plans to build a high-speed rail line from Las Vegas to Southern California—have entered a new chapter.
Specifically, Chapter 11.
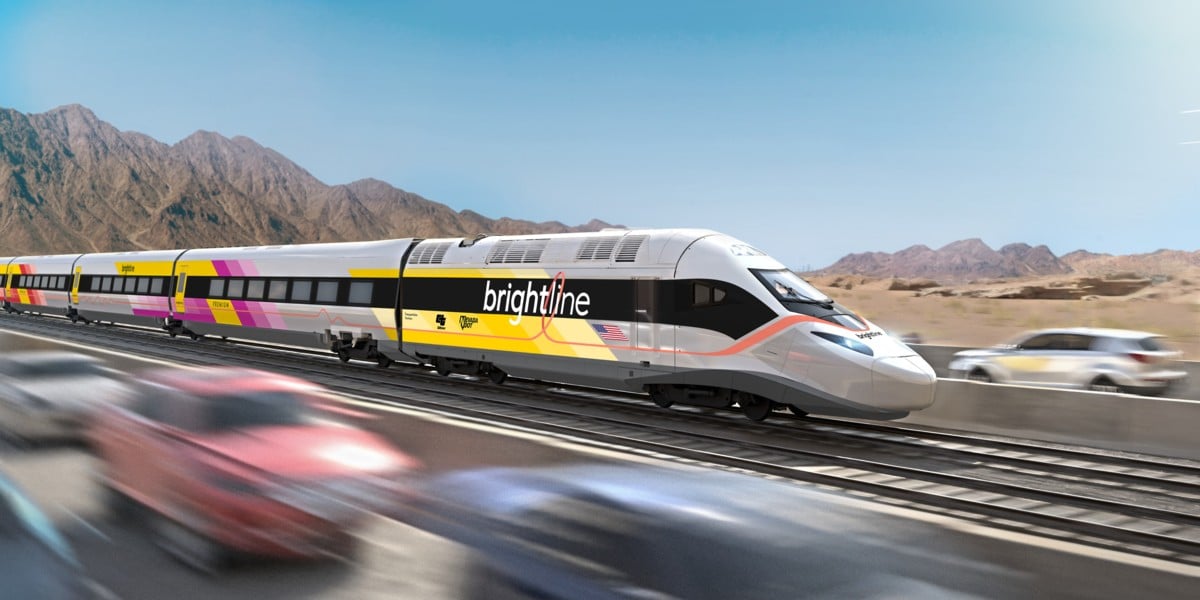
Brightline Holdings and about 16 affiliates filed for bankruptcy protection last week in New Jersey. They entered a restructuring support agreement with existing investors to pump $490 million more into the Miami-to-Orlando railroad. The company that actually operates those trains, Brightline Trains Florida, did not file, and service there is continuing.
Brightline West is a separate legal entity with overlapping ownership, rather than a wholly owned subsidiary of the Florida railroad. A company spokesperson told the Las Vegas Review-Journal that the Florida bankruptcy “has no bearing” on the Vegas project and that Brightline West’s “focus remains on completing the financing … and moving the project forward.”
Only there hasn’t been any visible progress in quite some time.
Slow Train Coming
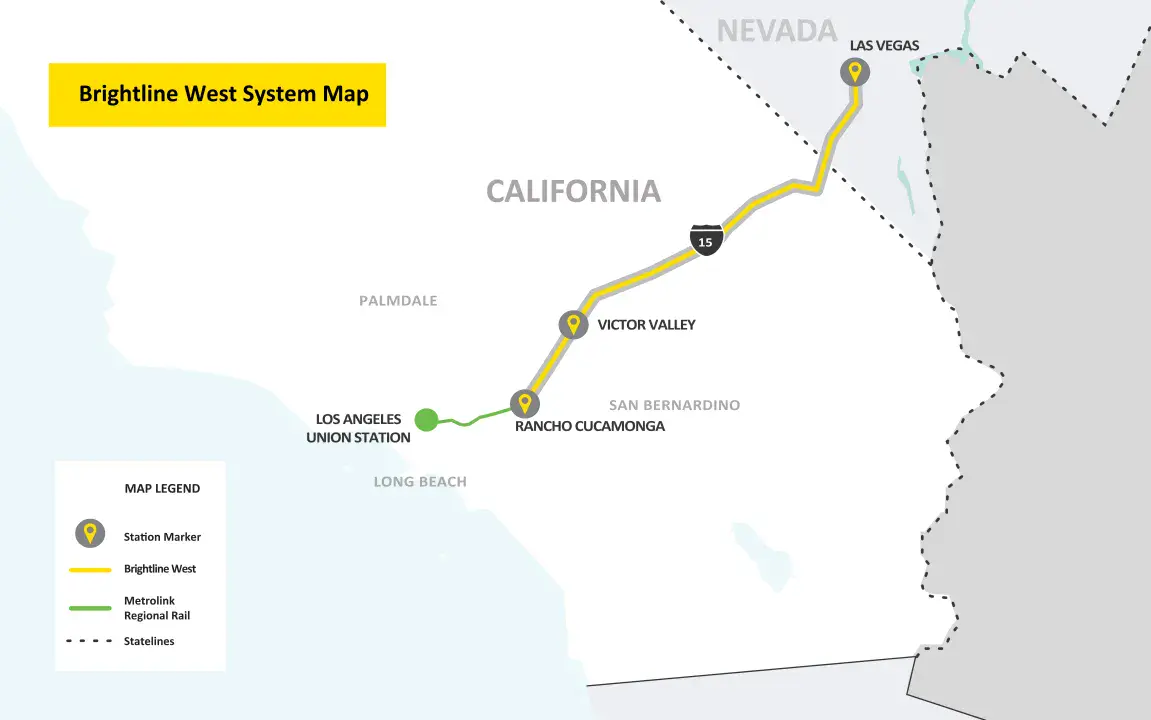
Fortress-backed Brightline took over the earlier XpressWest plan in 2018 and renamed it Brightline West in 2020. The line is supposed to run 218 miles from a station site on Las Vegas Boulevard—between Blue Diamond and Warm Springs roads—to Rancho Cucamonga, Calif., with additional stops in Hesperia and the Victor Valley.
In Rancho Cucamonga, riders would transfer to Metrolink for Los Angeles.
The company originally hoped to finish in time for the 2028 Olympic Games in Los Angeles. That date was already gone before the Florida filing. Brightline West’s completion target is now late 2029.
After a ceremonial groundbreaking in April 2024, the project’s estimated price tag nearly doubled, from about $12.4 billion to $21.05 billion, according to federal project documents and subsequent reporting.
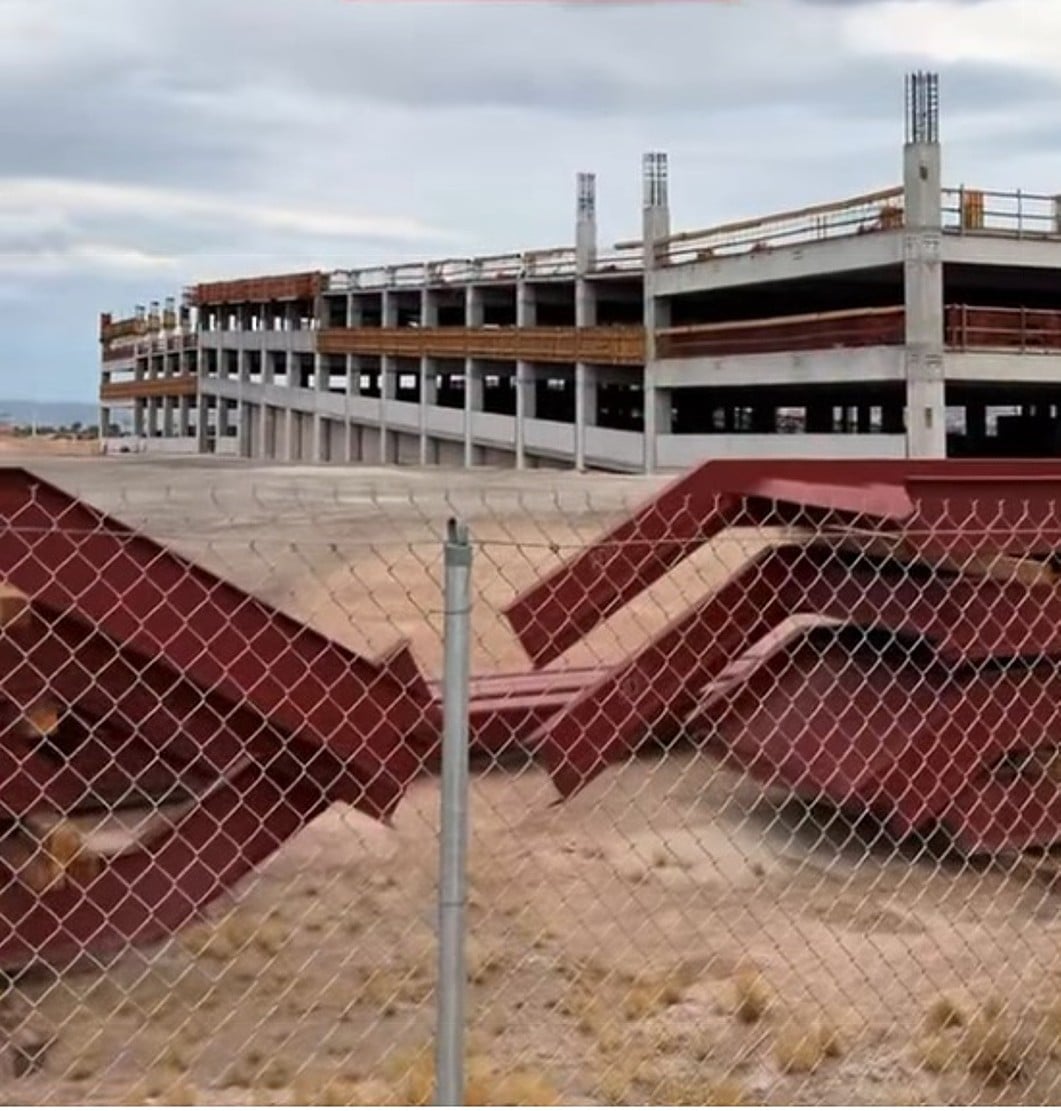
Early site work on the Las Vegas terminus began in 2025 on about 110 acres. It included grading, sewer and storm-drain work, and the start of a parking garage. But activity on the site now appears stalled. Crews have not been seen at the parking garage for at least six months, and no new construction phase has been announced.
Heavy construction—laying track in the I-15 median across the Mojave—still has yet to begin.
Waiting for the Money Train
Brightline West has a $3 billion federal grant and $2.5 billion in private-activity bonds. It is still seeking a $6 billion federal Railroad Rehabilitation and Improvement Financing loan. Brightline West has said the loan is a key component of its revised financing plan.
As of the latest available reporting, the loan had not been approved. Brightline West was still undergoing the federal review process, with the Build America Bureau continuing its creditworthiness review.
The Florida bankruptcy does not automatically affect Brightline West, which remains a separate entity. But it adds another financial complication around a project that is already seeking billions of dollars in additional financing.
Brightline West has raised roughly $5.5 billion toward its approximately $21.05 billion project cost, leaving a funding gap of roughly $15.5 billion.
A private railroad that still needs billions in additional financing, a federal loan application that remains unresolved, and a Las Vegas station site where construction appears to have stalled are not signs of a project racing toward 2029.
Until that financing is secured and major rail construction begins in the I-15 median, Brightline West remains a groundbreaking, a half-built parking garage, and a promise to speed tourists from California to Vegas that doesn’t seem to be moving closer to reality.


Conversation (0)
Be the first to comment on this article.